


Market Insights Snapshot
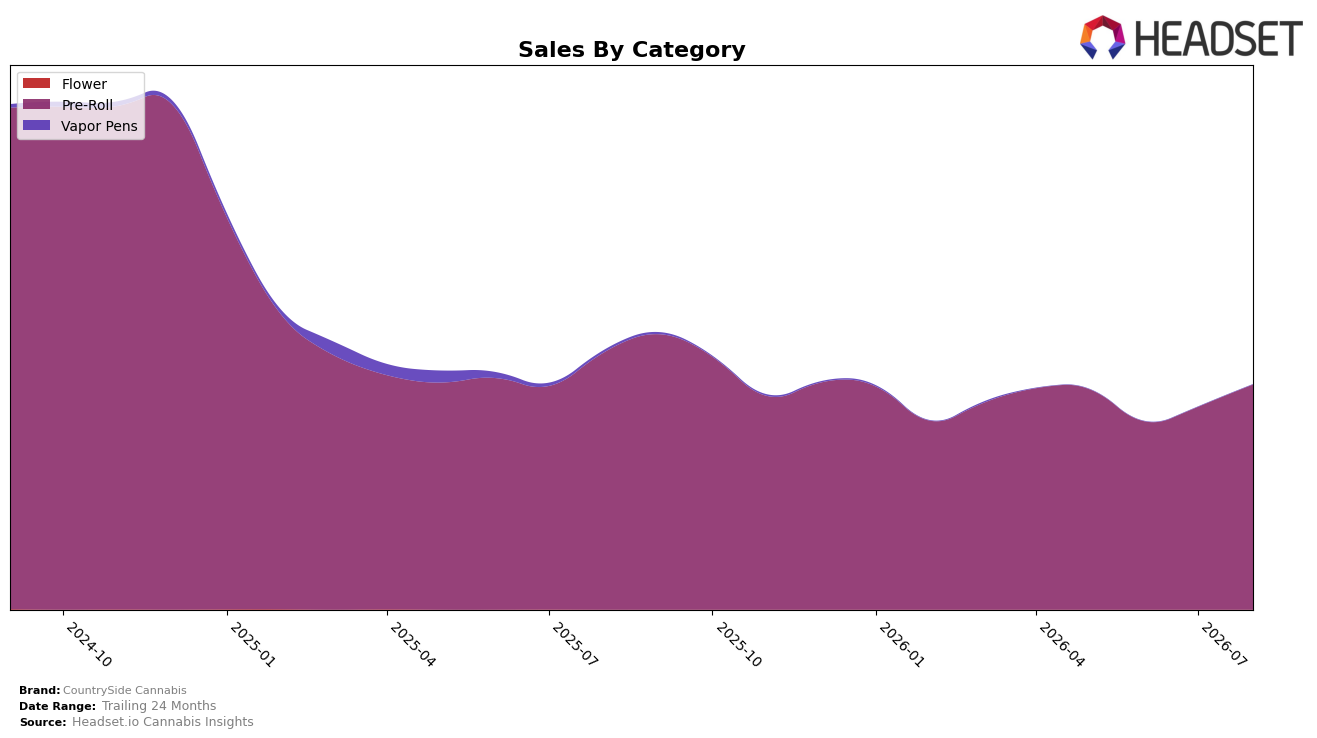
CountrySide Cannabis is concentrated entirely in Pre-Roll at 100.0% share, with August 2026 Pre-Roll sales up 11.06% month over month but down 12.50% year over year; at the brand level, sales fell 13.19% year over year while average price declined 0.41%. In Ontario, the brand’s Pre-Roll rank sat at 45, indicating mid-pack positioning despite the month-over-month lift, and the 24-month sales contraction of 59.38% frames the current uptick as recovery rather than expansion; the pattern implies a single-category dependency where monthly volatility can move headline results without diversifying risk.
With 100.0% exposure to Pre-Roll and a rank of 45 in Ontario, the 11.06% month-over-month growth versus a 12.50% year-over-year decline suggests share defense is occurring through tactical pricing (−0.41% average price year over year) rather than assortment breadth. The 59.38% 24-month sales drop, alongside August 2026’s category-only rebound, implies that sustaining position will require either climbing 5–10 rank spots within Pre-Roll or reintroducing a second category to smooth the 11–13% swing bands now driving brand-level outcomes.
Competitive Landscape
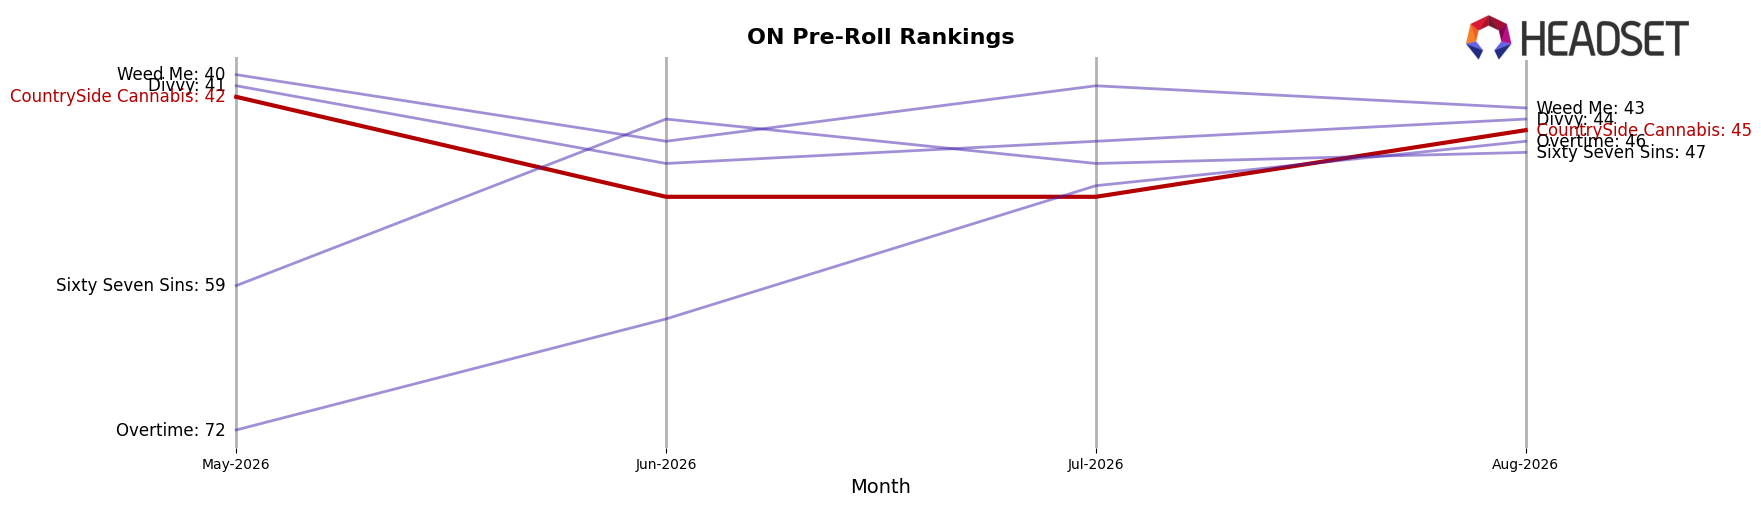
CountrySide Cannabis sits at rank #45 in ON Pre-Roll for August 2026, down 11 positions year over year from #34, and 3 spots below its May 2026 placement at #42; the brand’s historical peak was #15 in November 2024, marking a 30-place decline from that high. Meanwhile, Back Forty / Back 40 Cannabis moved from #2 to #1 alongside a 56.6% year-over-year sales increase, and Spinach climbed from #14 to #5 with an 81.6% year-over-year gain, indicating that CountrySide Cannabis is ceding rank to competitors that converted double-digit growth into top-5 positions. With General Admission slipping from #1 to #2 on a 28.1% sales decline while Thumbs Up Brand jumped from #10 to #3 on 70.7% growth, the pattern points to share consolidating in faster-growing leaders and suggests CountrySide Cannabis’s downward rank trajectory implies loss of relative momentum and a need to re-enter the top-30 to avoid further visibility erosion.
Notable Products
10th Planet Pre-Roll 10-Pack (5g) delivered the standout movement in August 2026 with a month-over-month increase of 18.1% and held rank 2, while Strawberry OG Pre-Roll 10-Pack (5g) rose 8.8% and remained at rank 1. Harvest Reserve - Grape Diamonds Pre-Roll (1g) declined 5.9% at rank 3, and Ethos Glue Pre-Roll 10-Pack (5g) grew 12.5% at rank 4, indicating that three of the top four ranks are anchored by multi-pack Pre-Roll formats. With Pre-Roll products occupying ranks 1 through 4 and only one single Pre-Roll showing a decline of 5.9%, the mix points to CountrySide Cannabis consolidating around value-oriented multi-pack Pre-Rolls to defend share and drive repeat velocity even as single-stick offerings soften.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

