

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Hi*AF is stocked at 125 licensed dispensaries across New York and Maryland, 75 of them in New York, with the deepest coverage in New York, Queens, Brooklyn, Buffalo, and Niagara Falls. Search by ZIP code or city below to find the closest one.
Market Insights Snapshot
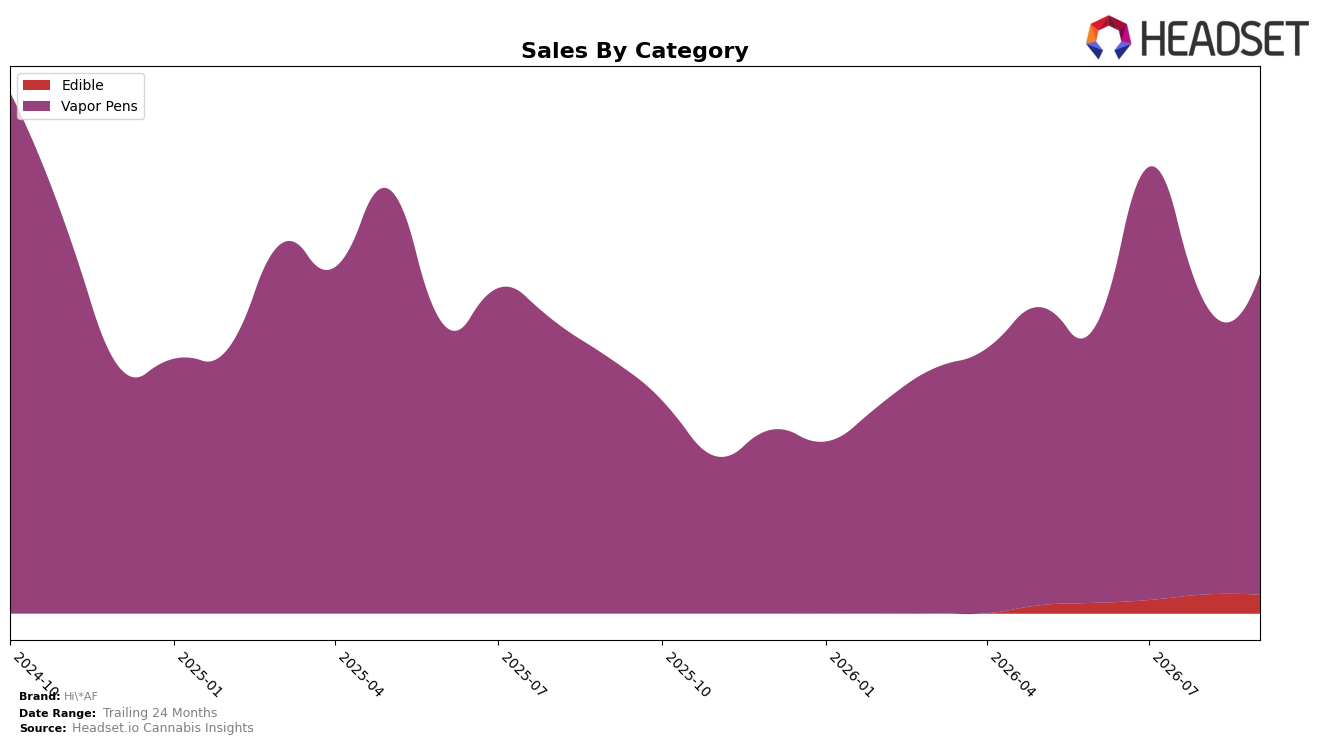
Hi*AF concentrated 94.56% of September 2026 sales in Vapor Pens, with Edible comprising 5.44%; within Vapor Pens, year-over-year sales rose 25.27% while month-over-month advanced 9.82%. Edible contracted month-over-month by 1.60% and lacks a year-over-year comp, while the brand’s average price fell 19.21% YoY to $28.65 even as total brand sales grew 32.48% YoY; the brand ranked 24 in Vapor Pens in Maryland. This pattern implies a price-led volume expansion concentrated in Vapor Pens and a tactical deprioritization of Edible, with category concentration magnifying rank outcomes in core markets.
Given a 24th-place rank in Vapor Pens in Maryland alongside a 9.82% MoM climb and 25.27% YoY growth in that category, Hi*AF’s competitive position is being driven by share capture within a single category rather than portfolio breadth. The 19.21% YoY price decline paired with 32.48% YoY brand sales growth suggests a deliberate elasticity play: trading price for velocity to improve placement within Vapor Pens while tolerating a 1.60% MoM pullback in Edible, implying a positioning bet on pen-centric identity and promotional cadence over multi-category diversification.
Competitive Landscape
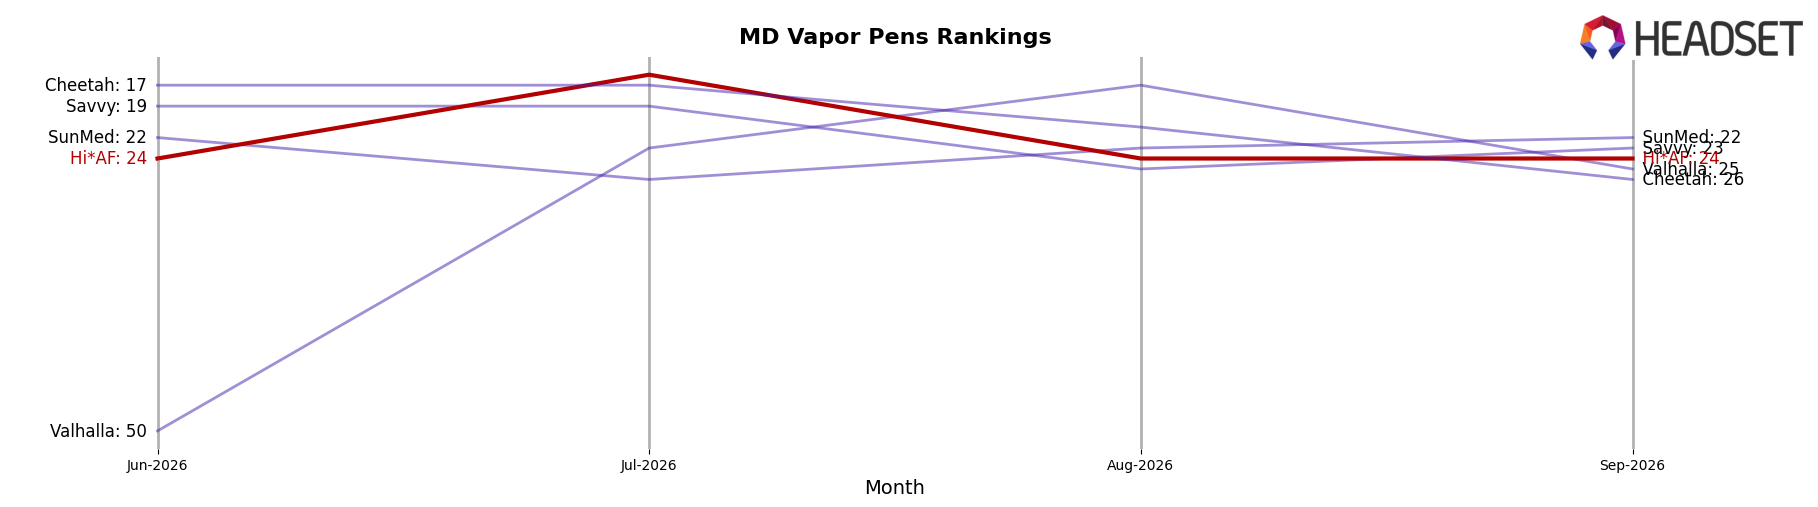
Hi*AF sits at rank #24 in MD Vapor Pens in September 2026, unchanged from #24 year over year, and also flat versus three months ago at #24; this stability contrasts with competitors’ movement as Rove advanced from #8 to #5 with 121.33% YoY sales growth while Hellavated climbed from #4 to #3 on 13.56% YoY growth. At the top, Select held #1 year over year with 34.12% YoY growth, whereas RYTHM slipped from #3 to #4 despite 0.51% YoY growth, indicating share is concentrating among faster risers; given Hi*AF’s prior peak at #13 in October 2024 and a sustained #24 since September 2025, the flat rank amid upward shifts by rivals implies a gradual erosion of relative competitiveness unless mix or distribution changes re-accelerate momentum.
Notable Products
Raspberry Crave Distillate Cartridge (1g) posted the standout move in September 2026 with a +72.9% month-over-month surge, reaching rank 2, while Strawberry Gummy 20-Pack (100mg) fell -14.3% at rank 3. Blue Raspberry Gummy 20-Pack (100mg) inched up +6.8% at rank 1, and Juicy Red Apple Distillate Cartridge (1g) slid -26.1% at rank 7. With six of the top ten belonging to Vapor Pens and one SKU delivering a single-month increase over +50%, the mix signals a pivot toward inhalables over edibles despite a gummy still holding the top rank.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

