

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Manzanita Naturals is stocked at 54 licensed dispensaries across California, with the deepest coverage in Los Angeles, San Francisco, Santa Ana, San Diego, and San Jose. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
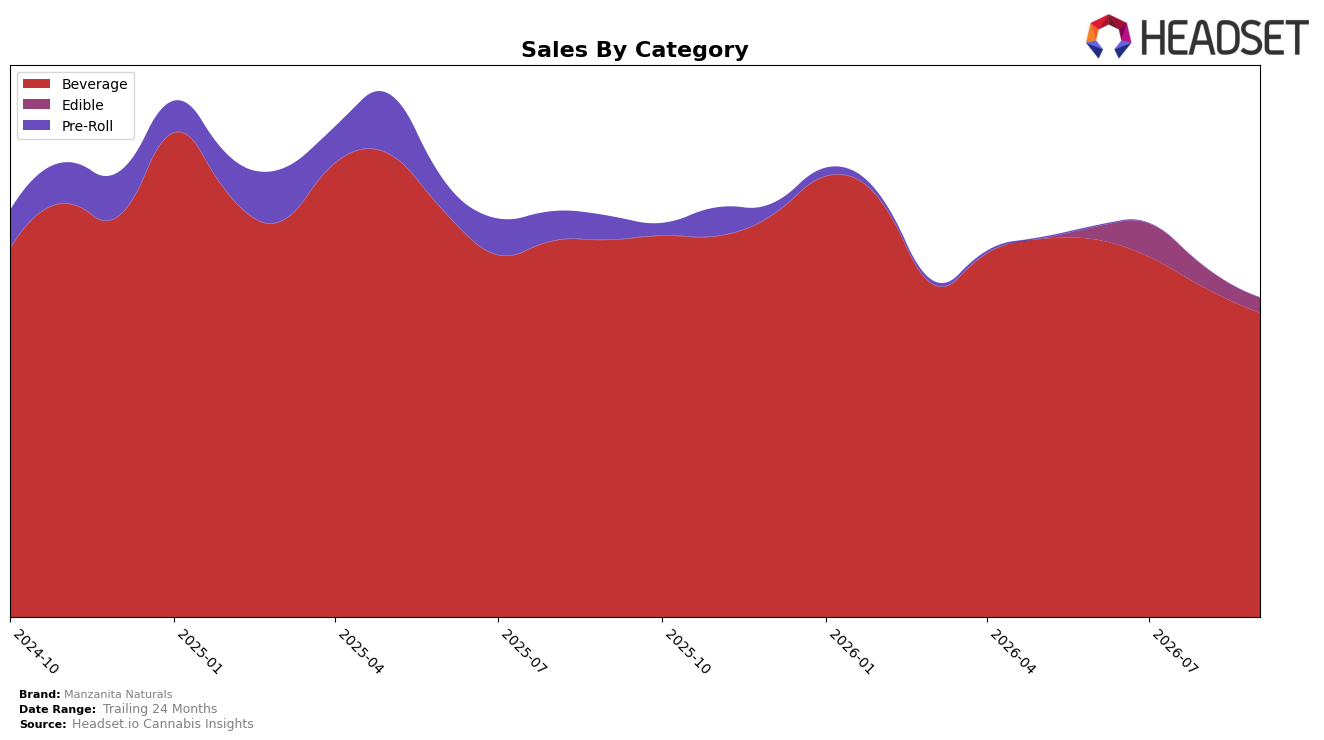
In September 2026, Beverage accounted for 95.32% share with a year-over-year decline of 19.36% and a month-over-month drop of 7.62%, while Edible held 4.68% share with a month-over-month decline of 27.79% and no year-over-year baseline. Against a total brand sales year-over-year change of -20.36% and an average price decrease of 6.71%, Beverage’s contraction outpaced price deflation, and Edible’s sharper month-over-month slide compressed diversification; the pattern implies a concentration risk where category dependence is amplifying volatility rather than offsetting it.
Manzanita Naturals held rank 7 in Beverage in California, a placement that, combined with Beverage’s 95.32% mix and a 7.62% month-over-month volume contraction, indicates mid-tier visibility but limited buffer if category headwinds persist. With Edible at 4.68% share and a 27.79% month-over-month decline versus the overall brand’s -20.36% year-over-year trend, the shifts imply that current positioning is anchored to a single category where incremental share gains must come from execution within Beverage rather than portfolio balancing.
Competitive Landscape
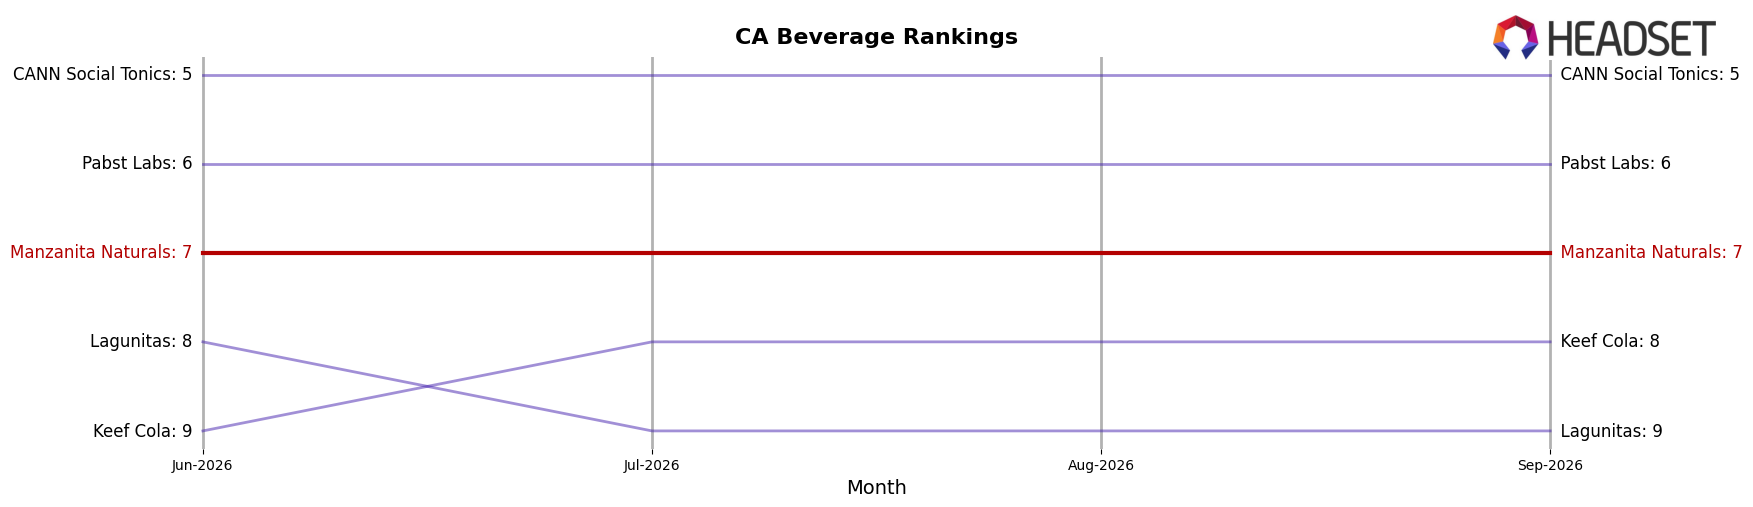
Manzanita Naturals sits at rank #7 in CA Beverage for September 2026, slipping 2 positions year over year from #5 while holding flat versus the prior 3 months at #7, and its peak at #3 in November 2024 underscores a multi-quarter reversion from earlier momentum; in contrast, Almora Farms advanced from #6 to #4 as of September 2026 and CANN Social Tonics moved from #9 to #5 alongside a 340.8% YoY sales increase, indicating competitive displacement pressure from mid-tier climbers; with St Ides steady at #1 year over year and Uncle Arnie's steady at #2 while growing sales 21.3% YoY, the combination of Manzanita Naturals’ 2-rank YoY decline and rivals’ upward mobility points to a share consolidation pattern that implies further rank erosion unless distribution or velocity shifts reverse the trajectory.
Notable Products
The steepest decline came from Kwik Ease - Sativa Strawberry Haze Shot (100mg THC, 2oz), down 27.95% and sliding to rank 6, while The Fizz - Orange Cola Soda (100mg THC, 12oz, 355ml) fell 23.43% at rank 5, signaling pressure on higher-dose sodas. In contrast, The Fizz - Lime Sparkling Water (100mg THC, 355ml) rose 14.47% at rank 3 and The Fizz - Strawberry Sparkling Water (10mg THC, 12oz, 355ml) gained 12.45% at rank 5, indicating momentum in sparkling formats even as The Fizz- Strawberry Sparkling Water (100mg THC, 12oz) dropped 16.55% at rank 4. Kwik Zzz's - Indica Kushberry Shot (100mg, 2oz, 59ml) held rank 1 with a 3.56% lift and $40,889 in September 2026, while five of the top ten are The Fizz SKUs, concentrating demand in the Beverage line but splitting it between 100mg and 10mg variants. This mix implies Manzanita Naturals is tilting toward flavor-forward, sessionable sparkling water while legacy 100mg shots and colas face cannibalization and dosage rebalancing.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

