

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Classix is stocked at 10 licensed dispensaries across Illinois, California, and 2 other states, 5 of them in Illinois, with the deepest coverage in Chicago, Joliet, Quincy, and Villa Park. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
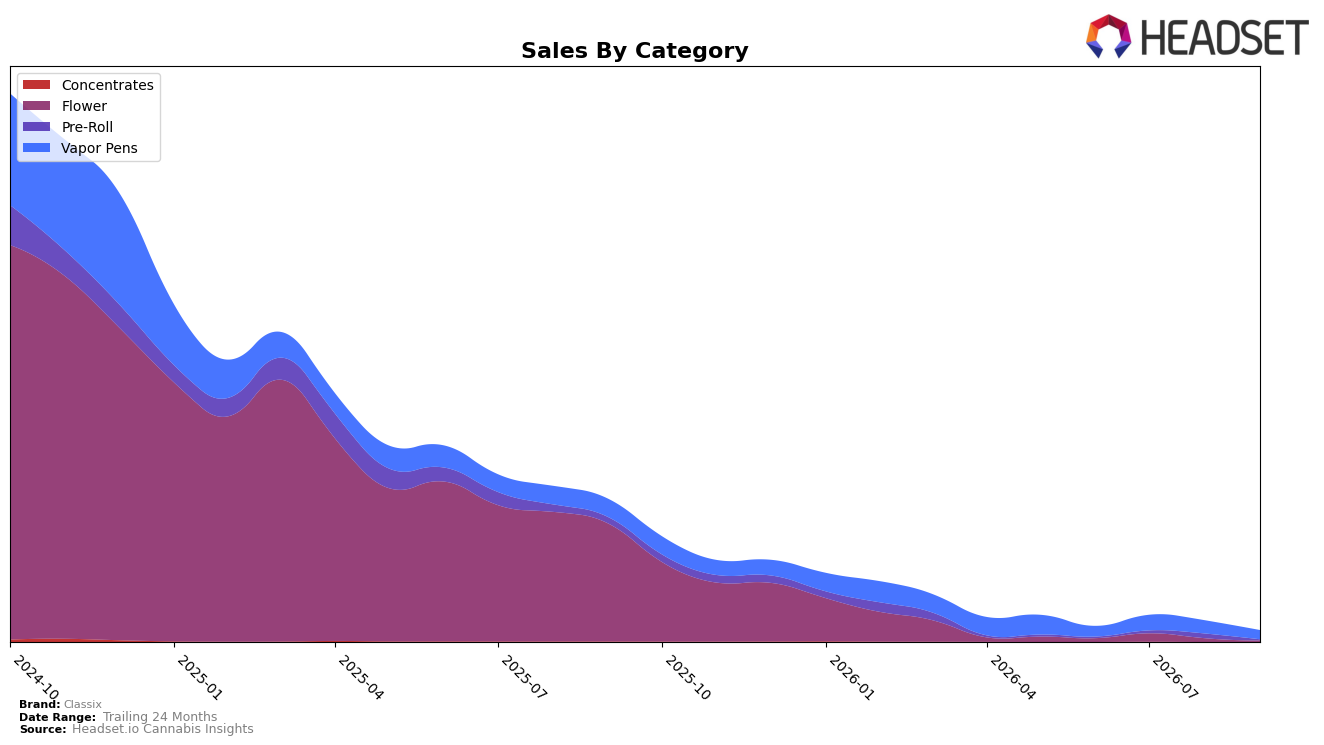
In September 2026, Classix concentrated 81.03% of sales in Vapor Pens, with Flower at 12.07% and Pre-Roll at 6.75%, while Concentrates rounded out just 0.15% — a mix now heavily skewed toward one category. Vapor Pens declined 50.70% year over year and 31.28% month over month, while Flower fell 98.88% YoY and 62.15% MoM, and Pre-Roll dropped 87.78% YoY and 83.05% MoM. Against this backdrop, average price fell 45.36% YoY to $13.98 and Vapor Pens pricing sat at $18.03, indicating a rapid move down-market. The pattern implies Classix is relying on Vapor Pens to carry a shrinking base while deep price cuts and sharp MoM pullbacks in Flower and Pre-Roll compress breadth and limit recovery paths.
The category skew coincides with a rank of 49 in Vapor Pens in Maryland, where a mid-pack position pairs with a 31.28% MoM contraction and an 81.03% brand mix exposure to that category. With brand sales down 92.31% YoY and 98.49% over 24 months, the 12.07% share in Flower and 6.75% in Pre-Roll no longer diversify risk, and the 83.05% MoM plunge in Pre-Roll especially reduces trial and cross-category capture. This implies Classix’s positioning is narrowing to price-sensitive Vapor Pen shoppers, with limited insulation from category volatility and fewer entry points for higher-ticket shoppers despite Flower’s $33.74 average price.
Competitive Landscape
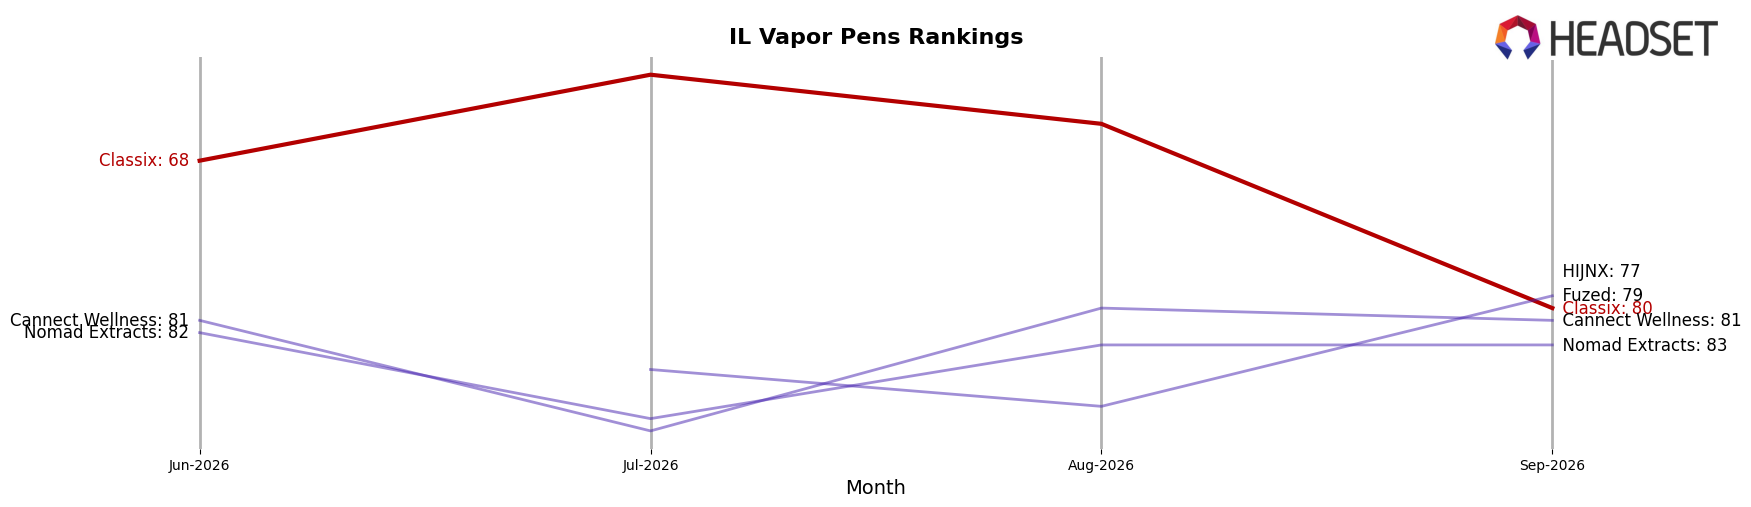
Classix sits at rank #80 in Illinois Vapor Pens in September 2026, falling 32 positions year over year from #48, and sliding 12 spots since June 2026 from #68, while its historical peak was #27 in December 2024; meanwhile, &Shine advanced from #2 to #1 with a 38.35% YoY sales increase and Fernway jumped from #13 to #3 on 308.84% YoY sales growth, indicating rivals are converting momentum into rank gains as Classix cedes share. With Select slipping from #1 to #2 despite 11.15% YoY growth and Savvy dropping from #3 to #5 alongside a -32.73% YoY decline, Classix’s move from #68 to #80 over the last three months and from #48 to #80 over the last year implies it is drifting toward the long tail where recovery to its December 2024 peak would require a material reversal in trajectory.
Notable Products
Scout's Honor Pre-Roll (1g) posted the steepest decline in September 2026 at -82.2% month over month while still holding rank 1, indicating a sharp contraction in a category that otherwise ceded prominence to Vapor Pens. Blue Dream Distillate Disposable (1g) fell -35.0% to rank 3 as Gelato Distillate Disposable (1g) slid -7.3% at rank 2, and six of the top ten are Vapor Pens, signaling a concentrated assortment where rank stability masks demand erosion. The -48.7% drop for Blue Dream Distillate Cartridge (1g) at rank 8 contrasts with OG Kush Distillate Disposable (1g) at rank 4 with a -2.9% dip, implying mix shift risk toward SKUs with smaller declines and a need to rebalance away from rapidly softening Blue Dream variants.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

