

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
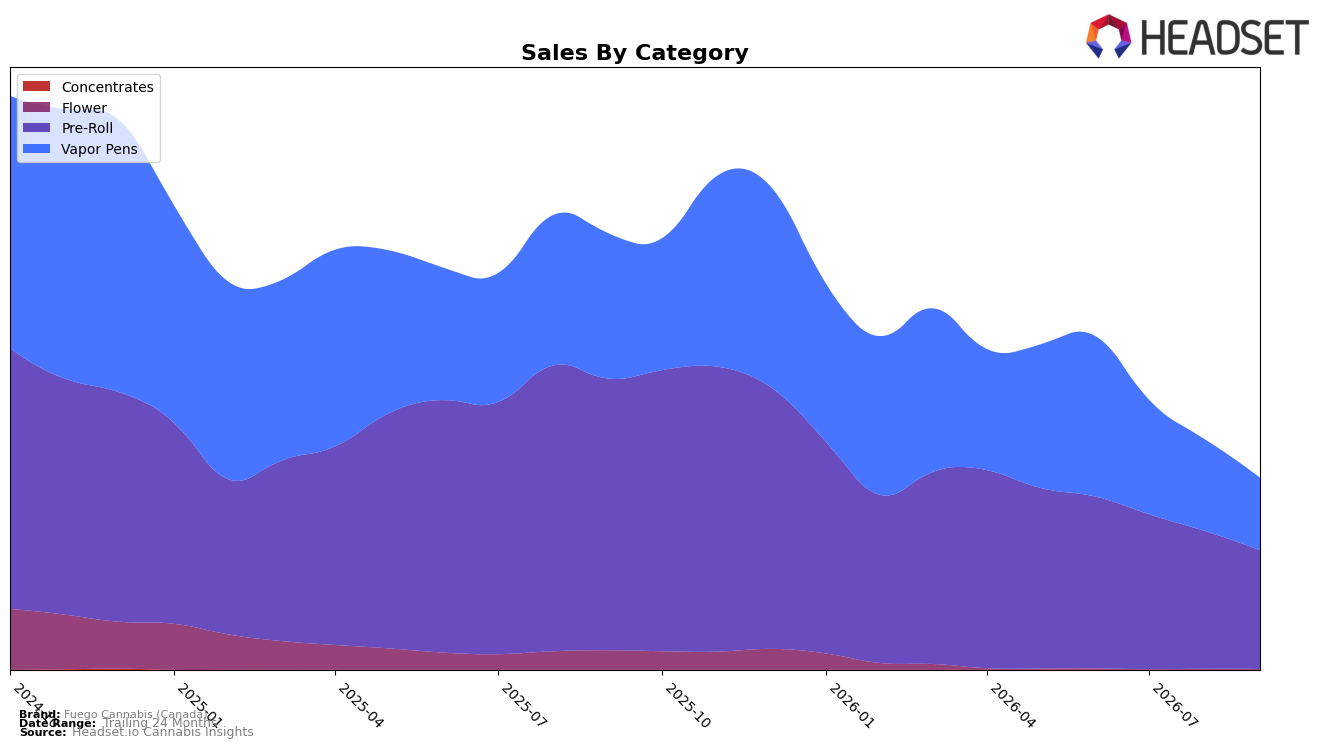
In September 2026, Fuego Cannabis (Canada) concentrated 61.90% share in Pre-Roll with a year-over-year decline of 56.35% and a month-over-month drop of 13.86%, while Vapor Pens held 37.78% share with a 50.15% YoY decline and a 20.96% MoM slide; Flower was reduced to 0.33% share after a 96.77% YoY contraction and a 25.41% MoM decrease. The weighted average price rose 11.65% YoY to $12.60 as Pre-Roll averaged $9.24 and Vapor Pens $30.83, indicating mix pressure toward lower-priced units even as overall prices increased; taken together with a Pre-Roll rank of 16 in Saskatchewan, the pattern implies a volume-led retrenchment anchored in Pre-Roll where rank stability may depend on defending mid-pack positioning while higher-priced Vapor Pens recede.
With Vapor Pens falling 20.96% MoM versus Pre-Roll’s 13.86% MoM decline and a 56.08% brand-level YoY drop alongside a 69.05% 24-month contraction, the portfolio is tilting toward value-accessible formats that can support traffic but compress revenue per buyer. Given Pre-Roll’s 61.90% share and a category rank of 16 in Saskatchewan, the direction suggests prioritizing regional Pre-Roll depth to preserve rank while selectively pruning low-velocity Flower (0.33% share, 96.77% YoY decline) and recalibrating Vapor Pens’ price-pack architecture to arrest faster MoM erosion, implying a defense-first stance that trades premium penetration for steadier throughput.
Competitive Landscape
Fuego Cannabis (Canada) sits at rank #28 in ON Pre-Roll for September 2026, down 19 positions from rank #9 year over year and 13 positions from rank #15 three months ago, while its historical peak at rank #7 in December 2025 frames the scale of the retreat; in contrast, Back Forty / Back 40 Cannabis climbed from #2 to #1 with 46.6% YoY sales growth, and Spinach advanced from #17 to #4 on 141.2% YoY growth. With General Admission slipping from #1 to #2 alongside a 38.2% YoY sales decline and Thumbs Up Brand moving from #8 to #3 on 62.1% YoY growth, the competitive set is reshuffling toward faster movers, implying Fuego Cannabis (Canada)’s rank trajectory signals share ceding to rivals accelerating up the table rather than a broad market contraction.

Notable Products
Galactic Fire Pre-Roll 2-Pack (2g) posted the steepest shift in September 2026 with a -50.6% month-over-month drop while falling to rank 8, as Sunny Daze Pre-Roll 2-Pack (2g) in rank 1 rose +8.3% and Night Rider Pre-Roll (1g) slid -25.4% at rank 4. Four of the top ten are single 1g Pre-Rolls that all declined between -14.1% and -32.5% while two-pack formats split directions with +13.4% for Dream Weaver Pre-Roll 2-Pack (2g) at rank 7 versus the -50.6% for Galactic Fire Pre-Roll 2-Pack (2g), indicating consumer trade-up is selective by strain rather than uniformly favoring multipacks.
Red Maui Wowie Liquid Diamonds Cartridge (1g) dropped -31.5% at rank 10 compared with a near-flat -0.5% for Sunny Daze Pre-Roll 4-Pack (4g) at rank 9, and Night Rider Pre-Roll 2-Pack (2g) eased a milder -5.4% at rank 2 beside the -14.1% for Sunny Daze Pre-Roll (1g) at rank 3. With Pre-Rolls occupying ranks 1 through 9 and one Vapor Pens SKU at rank 10, the mix implies Fuego Cannabis (Canada) is consolidating around Pre-Rolls while pruning or repositioning underperforming single-gram variants and select strains in multipack and vape.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

