

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
The Fresh Canna is stocked at 332 licensed dispensaries across Michigan, with the deepest coverage in New Buffalo, Detroit, Monroe, Grand Rapids, and Lansing. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
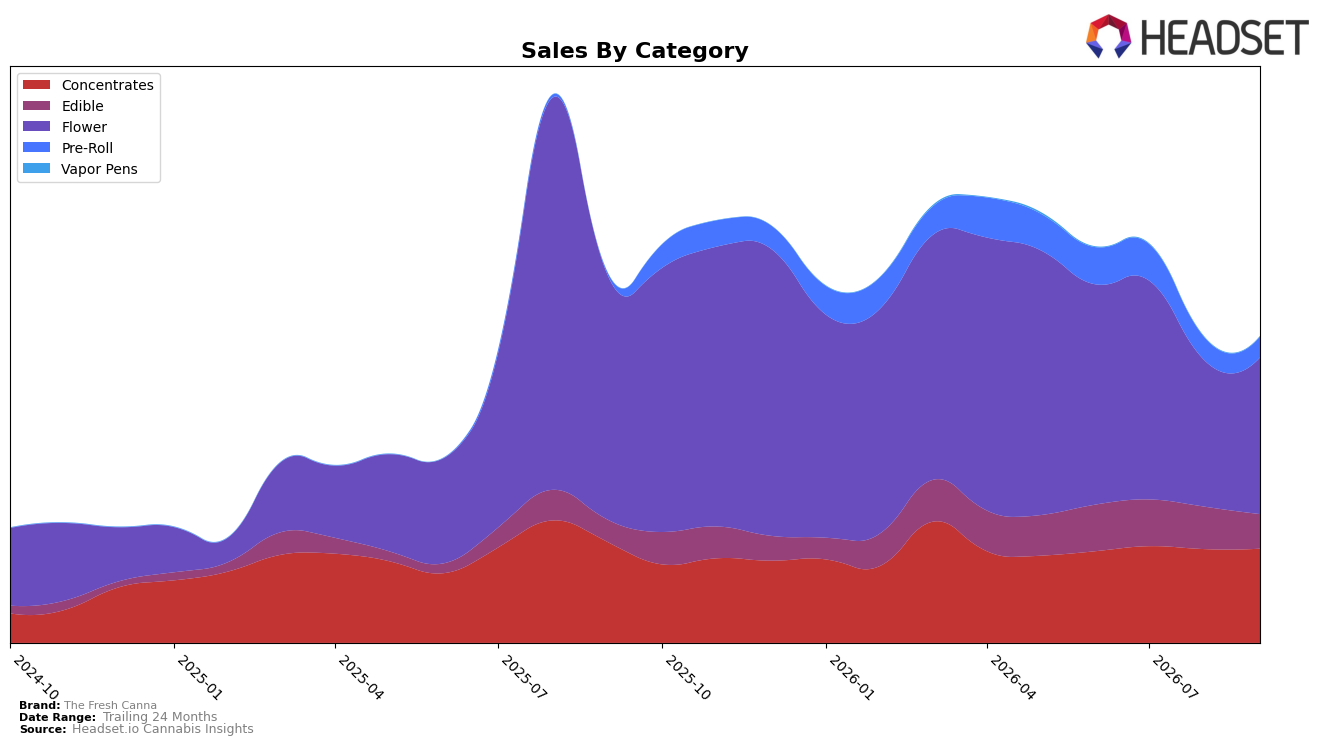
In September 2026, The Fresh Canna’s mix is anchored by Flower at 51.19% share with a 7.15% month-over-month lift but a 35.76% year-over-year decline, while Concentrates hold 30.76% share with a 0.48% MoM uptick and a 6.34% YoY drop. Edible accounts for 11.21% share with a 55.55% YoY increase but an 18.69% MoM pullback, and Pre-Roll sits at 6.77% share with a 778.19% YoY spike paired with an 8.31% MoM decline; Vapor Pens are negligible at 0.07% share with a 44.46% MoM slide. With total brand sales down 17.01% YoY and average price down 7.55% YoY, the pattern implies a pivot toward value and mix rebalancing: near-term growth depends on stabilizing Flower’s YoY erosion while harvesting Edible’s YoY momentum and converting Pre-Roll’s surge into sustained contribution.
The category shifts indicate that reliance on Flower in Michigan introduces rank pressure at rank 34 in Flower, as the 35.76% YoY Flower decline counteracts the 7.15% MoM recovery and limits share gains from smaller, faster-growing lanes. The 55.55% YoY rise in Edible alongside a 778.19% YoY jump in Pre-Roll signals elastic demand at lower average prices ($12.62 brand-wide) but their 18.69% and 8.31% MoM declines suggest volatility; positioning should emphasize sustained penetration in Edible and Pre-Roll while shoring up Flower mix so that month-over-month dips in smaller categories do not outweigh concentration risks in the largest one.
Competitive Landscape
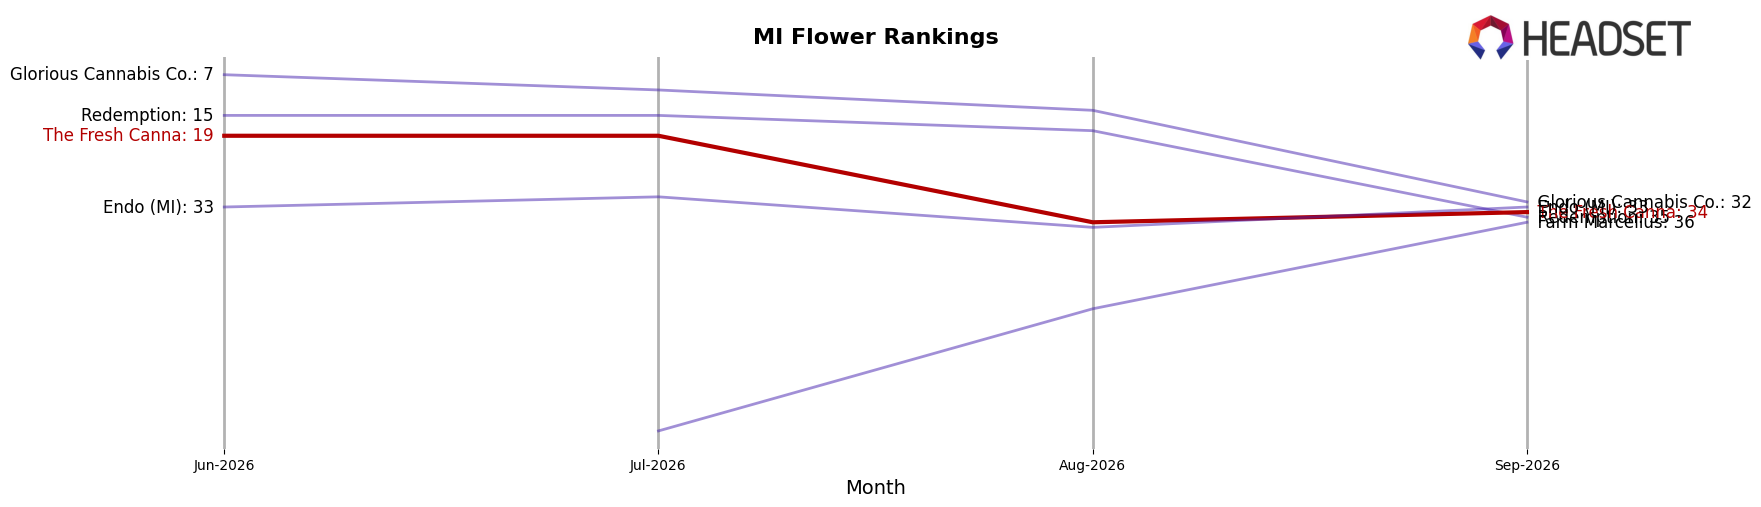
The Fresh Canna sits at rank #34 in Michigan Flower in September 2026, down 16 positions year over year from #18 and 15 spots below its June 2026 rank of #19, while still 21 places off its August 2025 peak of #13; meanwhile, High Minded held #1 both this year and last despite a -3.3% YoY sales change, and Play Cannabis climbed from #7 to #2 with +33.3% YoY sales, indicating that The Fresh Canna’s relative decline in rank and loss of 15 positions since June 2026 coincide with competitors gaining share at the very top, implying a drift from mid-tier contention toward the lower third unless mix or distribution is recalibrated.
Notable Products
Blue Dream Live Resin (1g) posted the steepest decline in September 2026 at -43.4% while slipping to rank 10, as Strawberry Cough Live Resin Gummies 5-Pack (200mg) fell -12.8% but still held rank 1. Red Raspberry Live Resin Gummies 5-Pack (200mg) dropped -24.5% at rank 3 versus Blueberry Gelato Live Resin Gummies 5-Pack (200mg) up 8.4% at rank 2, indicating flavor volatility within the same format. Eight of the top ten are Edible SKUs clustered between ranks 1 and 9, while Blueberry Live Resin Snowcaps (Bulk) in Flower in rank 6 grew 2.8% on $58,700 in sales, pointing to limited traction outside edibles. The pattern implies The Fresh Canna is consolidating around edibles for volume while concentrates act as a swing category that can drag overall momentum when a single SKU underperforms.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

