

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Jaunty is stocked at 311 licensed dispensaries across New York, with the deepest coverage in New York, Brooklyn, Queens, Buffalo, and Rochester. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
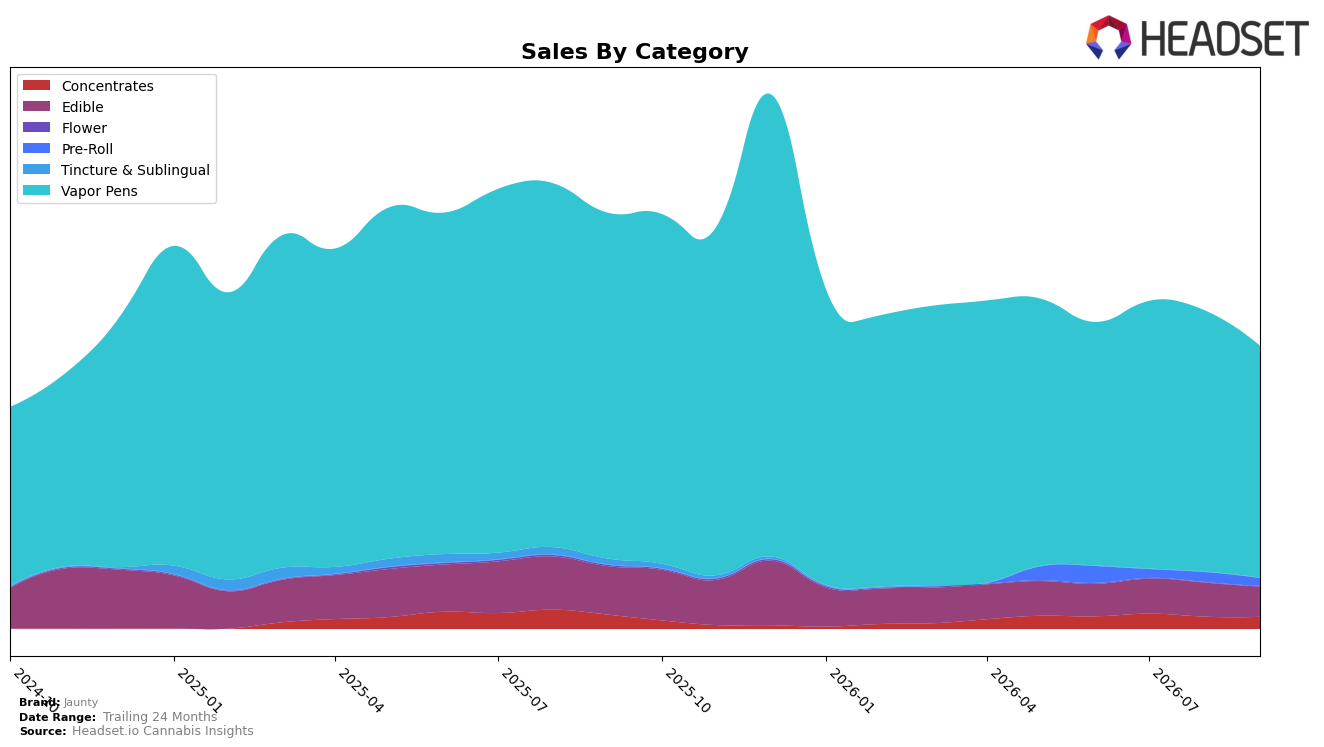
Jaunty’s mix in September 2026 is concentrated in Vapor Pens at 82.45% share with a year-over-year decline of 33.01% and a month-over-month drop of 11.30%, while Edible holds 10.62% share with a 37.86% YoY decline and an 11.37% MoM decline. Concentrates contribute 4.21% share with a smaller 15.36% YoY drop and a 1.33% MoM dip, and Pre-Roll—though only 2.68% share—posts a 55,326.13% YoY surge against a 20.60% MoM pullback; Flower is nearly exited at 0.04% share with an 87.08% YoY and 18.05% MoM decline. With average price down 13.59% YoY to $34.74 and Vapor Pens priced at $42.75, the brand is leaning on price accessibility while defending a category where it holds rank 2 in New York—the pattern implies dependence on a single category with early diversification green shoots but near-term compression across most lines.
The shift toward a lower-priced portfolio (average price down 13.59% YoY) alongside a category concentration where Vapor Pens fell 33.01% YoY yet still command 82.45% share indicates a value-led defense of its core rather than broad expansion. Concentrates’ comparatively smaller 15.36% YoY decline and minimal 1.33% MoM erosion suggest a viable secondary pillar, while Pre-Roll’s outsized 55,326.13% YoY growth from a tiny base and a sharp 20.60% MoM retreat points to test-and-learn rather than stable scale; this mix, coupled with a rank of 2 in New York Vapor Pens, implies that near-term positioning hinges on protecting share in one anchor category while selectively nurturing Concentrates to reduce volatility.
Competitive Landscape
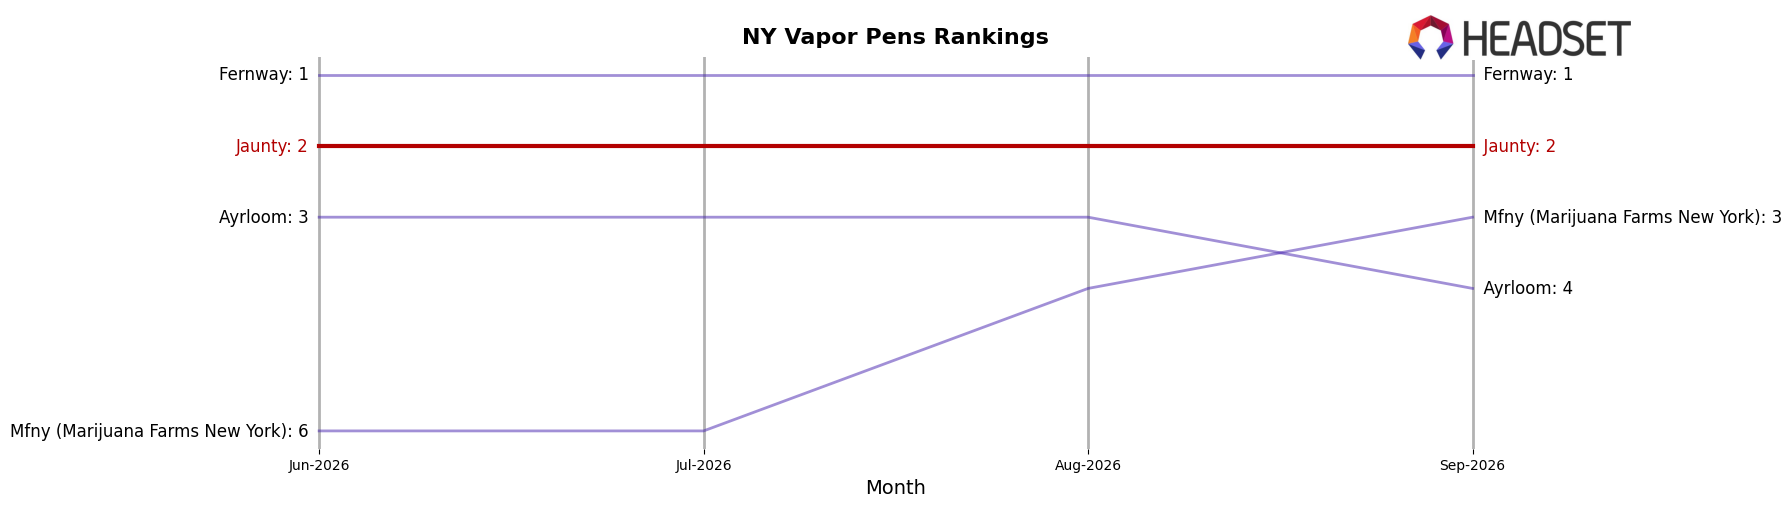
Jaunty sits at rank #2 in NY Vapor Pens in September 2026, down 1 position year over year from #1, with stability versus June 2026 at #2 and a prior peak at #1 in May 2026; meanwhile, Fernway holds #1 after improving from #3 year over year and Ayrloom slipped from #2 to #4 alongside a -24.9% YoY sales change. Competitive pressure is widening as Jetty Extracts surged from #28 to #5 with +289.4% YoY sales and Mfny (Marijuana Farms New York) moved from #5 to #3 with +40.5% YoY sales, while Fernway advanced from #3 to #1 with +18.1% YoY; the pattern implies Jaunty’s slippage from #1 to #2 is less about recent decline and more about faster-rising competitors compressing headroom at the top.
Notable Products
Palms - Blue Dream Distillate Disposable (1.5g) posted the steepest decline in September 2026 at -13.4% MoM while dropping to rank 5, and Classic - Amnesia Haze Distillate Cartridge (1g) also fell -13.1% MoM at rank 7, indicating pressure within mid-pack Vapor Pens. In contrast, Classic - Sour Diesel Distillate Cartridge (1g) rose +6.4% MoM at rank 2 and Classic- Wedding Cake Distillate Oil Cartridge (1g) gained +2.1% MoM at rank 8, with four of the top ten being Vapor Pens inside ranks 2–9. The CBN/THC 1:1 Dreamberry Hash Gummies 10-Pack (100mg CBN, 100mg THC) held rank 1 despite a -1.1% MoM dip, while the CBG/THC 1:1 Orange Swirl Hash Rosin Gummies 10-Pack (100mg CBG, 100mg THC) entered at rank 10 with $43,553 and no MoM baseline. The pattern implies Jaunty is anchored by a stable Edible leader while Vapor Pens drive volume but carry higher month-to-month volatility, pointing to a portfolio that leans on a single Edible flagship while iterating SKUs to stabilize pen performance.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

