

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Ooowee is stocked at 195 licensed dispensaries across Washington, with the deepest coverage in Seattle, Tacoma, Spokane, Olympia, and Vancouver. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
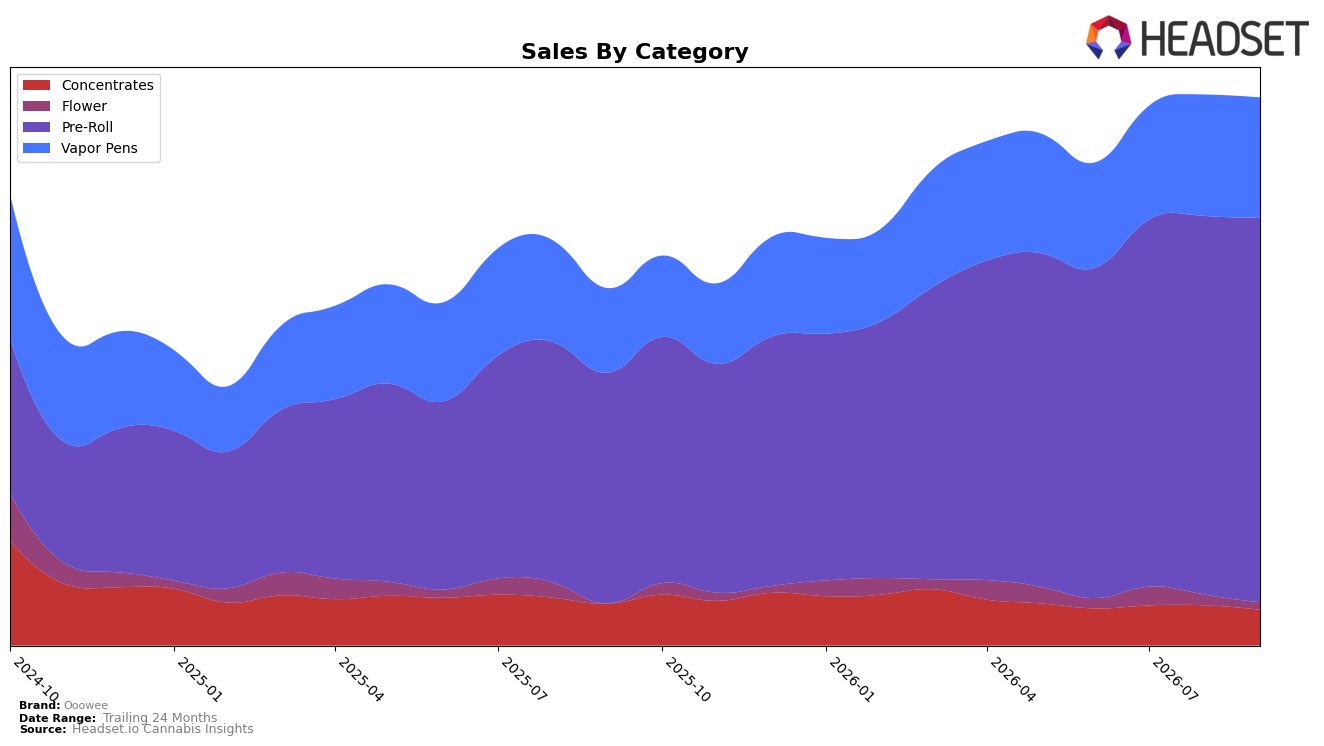
Ooowee concentrated 60.68% of September 2026 sales in Pre-Roll, where category sales grew 57.69% year over year and 1.50% month over month, while Vapor Pens held 22.54% share with 29.32% YoY but slipped 0.93% MoM. Concentrates accounted for 10.42% share with a -7.84% YoY and -5.82% MoM decline, and Flower at 6.36% share rose 19.72% YoY but fell 6.78% MoM; the brand’s average price rose 4.01% YoY alongside Pre-Roll’s $9.17 average price. With Pre-Roll ranked #1 in Washington and expanding faster YoY than Vapor Pens by 28.37 percentage points, the mix suggests Ooowee is anchoring growth in a single lead category while allowing secondary categories to cycle down MoM.
The widening YoY gap between Pre-Roll at 57.69% and Vapor Pens at 29.32%, coupled with Pre-Roll’s 1.50% MoM uptick versus negative MoM in Vapor Pens (-0.93%) and Flower (-6.78%), implies a defensive moat around the flagship segment and a need to re-tune assortment in lagging formats. Holding a #1 rank in Washington Pre-Roll while Concentrates contract both YoY (-7.84%) and MoM (-5.82%) indicates pricing and product depth should continue to weight toward Pre-Roll, with selective innovation in Vapor Pens to capture incremental share without diluting the 60.68% Pre-Roll mix.
Competitive Landscape
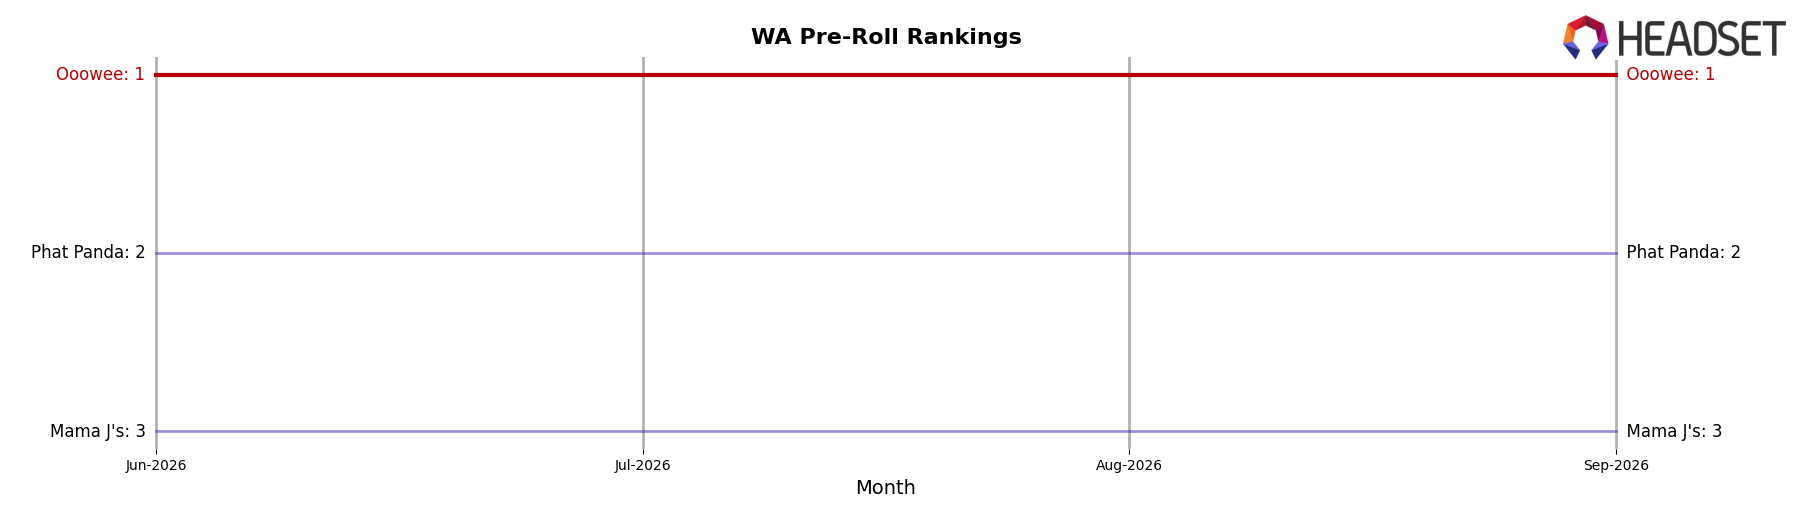
Ooowee ranks #1 in WA Pre-Roll in September 2026 and is flat year over year at #1, holding the same #1 position it had in September 2025, while also matching its June 2026 rank of #1; meanwhile, Phat Panda sits at #2 with a year-over-year hold at #2 despite a 7.61% sales increase, and Mama J's is #3 with a year-over-year hold at #3 alongside a 53.58% sales increase, indicating competitors are growing beneath a static rank ceiling. With Lifted Cannabis Co climbing from #5 to #4 year over year (+1 rank) and Stingers slipping from #4 to #5 year over year (-1 rank), the pack is reshuffling while Ooowee maintains a peak rank of #1 in September 2026; the pattern implies that sustained rank leadership now relies on defending share against faster-growing #3 and #4 players rather than chasing further upward movement.
Notable Products
Blueberry Dream Infused Pre-Roll 5-Pack (5g) posted the steepest decline at -16.7% while falling to rank 4, and FaceLock Pre-Roll 5-Pack (5g) also contracted -11.2% at rank 2, signaling that higher-profile SKUs lost momentum in September 2026. In contrast, Ooowee Marker Pre-Roll 5-Pack (5g) rose +13.4% to rank 5 as Lemon Cherry Gelato Pre-Roll 5-Pack (5g) inched up +0.8% at rank 8, but five SKUs between ranks 1 and 9 recorded MoM drops greater than -10% or near it (-14.7% at rank 7 and -13.7% at rank 9), concentrating weakness near the top of the chart. With nine of the top ten coming from the Pre-Roll category and only one single count format represented in the top nine, the mix implies Ooowee is overexposed to multi-pack Pre-Rolls and should rebalance toward formats that smooth volatility.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

